Over the past week, my phone has lit up more than usual.
Agents, team leaders, brokerage executives—all asking some version of the same question: What do you make of this AI panic? The market had just erased roughly $800 billion in value, reacting to a growing narrative that AI isn’t just improving productivity — it’s about to destabilize the entire white-collar economy. If you’ve been following commentary from outlets like The Kobeissi Letter, you’ve seen how quickly this argument spread.
The argument gaining traction is simple. Advanced AI systems compress margins, replace cognitive labor, and trigger a negative feedback loop: layoffs lead to weaker consumption, weaker consumption leads to slower growth, and housing—always sensitive to confidence, feels it next.
It’s a powerful argument. But it rests on one big assumption—that demand is fixed.
History doesn’t tend to support that view. When the cost of producing something drops dramatically, demand rarely stays flat. When computing became cheaper, we didn’t simply buy the same number of computers for less money; we built entirely new industries. When distribution moved online, commerce didn’t shrink. Instead, it expanded. Lower costs don’t automatically mean collapse. They often signal broader participation.
If you look at long-term U.S. labor productivity data from the Bureau of Labor Statistics, you’ll see that sustained productivity gains have historically coincided with rising living standards—even through periods of disruption.
So what does this have to do with residential real estate brokerage?
Quite a lot.
Real estate sits at the intersection of white-collar work, consumer confidence, mobility, and credit markets. If AI truly compresses cognitive labor, brokerage might look like an obvious casualty. After all, agents rely heavily on information processing: comparative market analyses, listing descriptions, marketing strategy, transaction coordination, contract review, and data interpretation. AI can already handle much of that, and it will only get better.
There’s no point pretending that part of the job won’t change. It will. The paperwork layer of brokerage is becoming cheaper and faster. Marketing production is accelerating. Data analysis is becoming more accessible. Tasks that once required hours now take minutes.
But margin compression in certain tasks does not equal industry collapse. It signals transition.
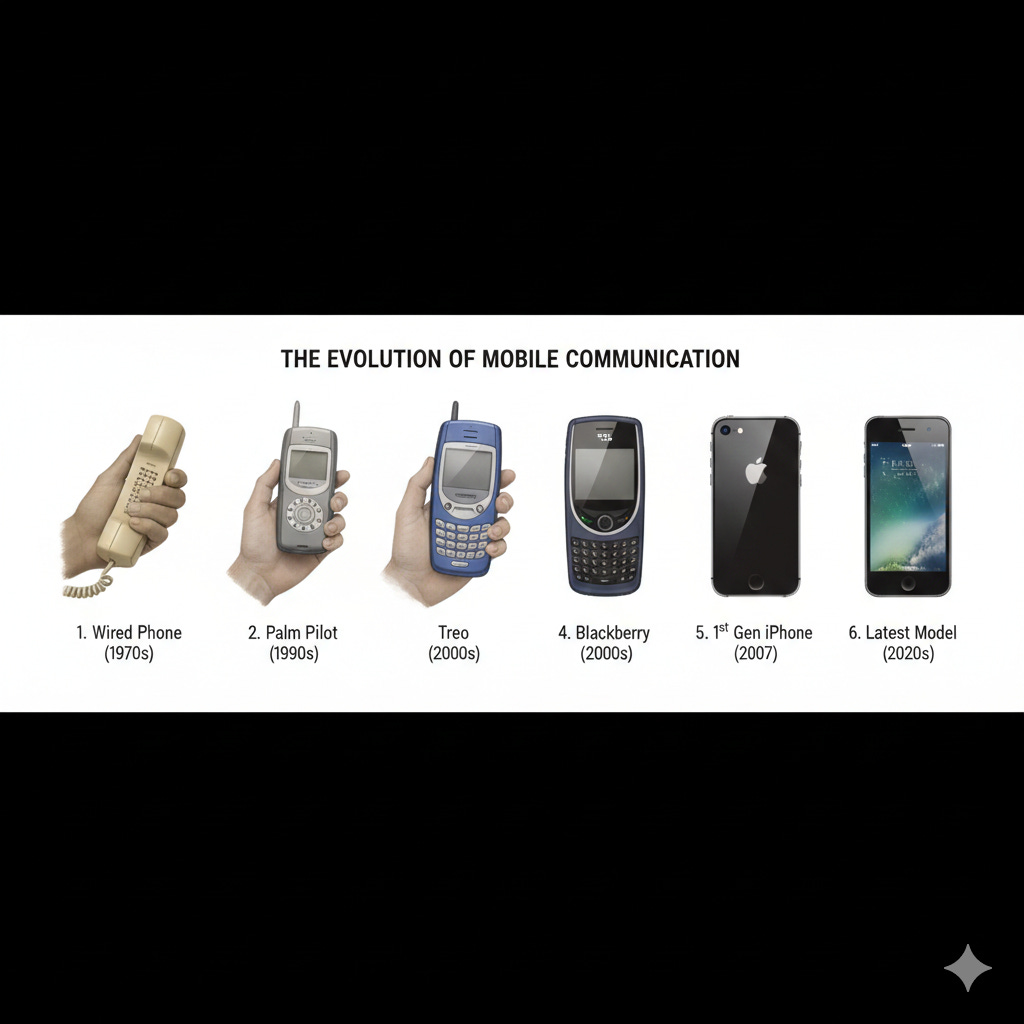
I’ve been in this business long enough to have seen multiple “this changes everything” moments. I watched classified ads disappear. I saw Craigslist disrupt rental marketing. I remember when a Palm Pilot felt revolutionary, then a Treo, then a BlackBerry, and finally the smartphone. Each device promised to make us more efficient and raised the unaskable question: would agents even be needed in the same way?
What actually happened was simpler. The best operators became more productive. The average ones stayed average. The technology didn’t eliminate brokerage. It exposed the gap between those who ran a business and those who simply held a license.
But I’ll admit something: this time feels different.
Over the past few months, AI has become such a valuable thought partner that it has started to feel like the best assistant I’ve ever had. It mapped out a day in Lisbon with more precision than any travel desk. It helped me create a comprehensive employee handbook in a fraction of the time it would have taken otherwise, a task we procrastinated on for months. Then it walked me step-by-step through what I needed to prepare for a loan application, clearly organizing every document and data point. It built a dynamic spreadsheet to project cash flows. It helped us visualize our new office at 67th and Madison — layout, paint colors, furniture, decor — before we moved a single piece. And perhaps most meaningfully, it’s accelerating something I’ve done for two decades: curating listings and advising clients based on experience.
It doesn’t replace that judgment — it sharpens it. Some days, it genuinely feels like a small miracle. That’s not dystopian. That’s leverage.
As I wrote in my book, The Pursuit of Home, a residential sale or purchase is far more than a collection of documents or a calculation of financial risk. It is an emotionally loaded event that intersects with family dynamics, timing, identity, fear, and aspiration. AI can generate a price range; it cannot sit across from a nervous seller and help them navigate doubt. It can summarize a contract; it cannot read the room when negotiations stall or sense when a buyer is about to overreact. It can draft language; it cannot take accountability when something goes wrong — and in real estate, something always does.
As knowledge becomes abundant, judgment becomes more valuable.
The larger question, then, is whether AI reduces demand for housing or reduces friction within housing. That distinction matters. A real estate market is full of inefficiencies: underwriting delays, compliance bottlenecks, marketing costs, valuation uncertainty, zoning complexity, renovation guesswork, and transaction coordination issues. Anyone who has shepherded a deal from listing to closing knows how much time and energy get lost in those seams.

If AI meaningfully lowers those frictions, transactions become easier. And when transactions become easier, volume can increase. Move-up buyers don’t wait as long. Investors transact more frequently. Cross-state relocations become smoother. Small developers analyze opportunities faster. First-time buyers gain better tools for decision-making. Velocity rises.
There’s an old saying in our industry that “time kills all deals.” If that’s true, reducing friction may be one of the most powerful tailwinds brokerage could ask for. This business has always run on momentum. That won’t change.
Yet the bearish narrative assumes that AI replaces income faster than it lowers costs. That may happen in certain sectors. But there is another plausible path: AI compresses service costs so dramatically that real purchasing power rises, even without explosive wage growth. If the cost of running a small business falls, entrepreneurship becomes more attainable. If administrative overhead drops, mobility increases. Housing demand has historically thrived in dynamic environments where people are building businesses, relocating, and making forward-looking decisions.
For broader housing context, the National Association of Realtors and the U.S. Census Bureau’s housing data consistently show how sensitive transaction volume is to confidence and financing efficiency — both areas where AI could reduce friction rather than demand.
Productivity is the quiet variable in all of this. Even a modest, sustained increase in productivity across construction, lending, compliance, and brokerage operations compounds over time. Faster underwriting, smarter build-cost modeling, more efficient marketing, and streamlined back-office functions increase capacity. Higher capacity supports more transactions per agent and more fluid markets overall.
The real risk to agents is not extinction. It is irrelevance for those who do not evolve.
An agent who uses AI thoughtfully, to analyze deeper, respond faster, personalize communication, and manage more volume—will gain leverage. The gap between high-skill, tech-enabled advisors and low-leverage operators will widen. We’ve seen this before. The internet didn’t eliminate agents. Online listings didn’t remove commissions. They reshaped margins and concentrated opportunity among those who adapted.
Nearly 70% of agents closed either zero or one deals in 2025—a statistic reflected in production distribution data from the NAR Member Profile. I can’t believe it, but it’s true. That level of part-time participation has long been a structural feature of the industry. If this cycle forces greater professionalism and commitment, that may not be collapse—it may be maturation.
It’s easy, in moments like this, to assume the worst-case scenario is inevitable. Markets tend to price fear before they price adaptation. But if AI lowers friction across the economy and expands participation rather than suppressing it, housing doesn’t freeze.
It becomes more fluid.
And in fluid markets, steady, adaptable operators don’t disappear.
They scale.
Scott Harris is the founder of Magnetic, a New York City–based residential real estate firm focused on thoughtful strategy and disciplined execution. He is the bestselling author of The Pursuit of Home: A Real Estate Guide to Achieving the American Dream (BenBella Books, 2025) ()and has spent more than two decades guiding buyers and sellers through multiple market cycles. Learn more at www.magneticre.com.